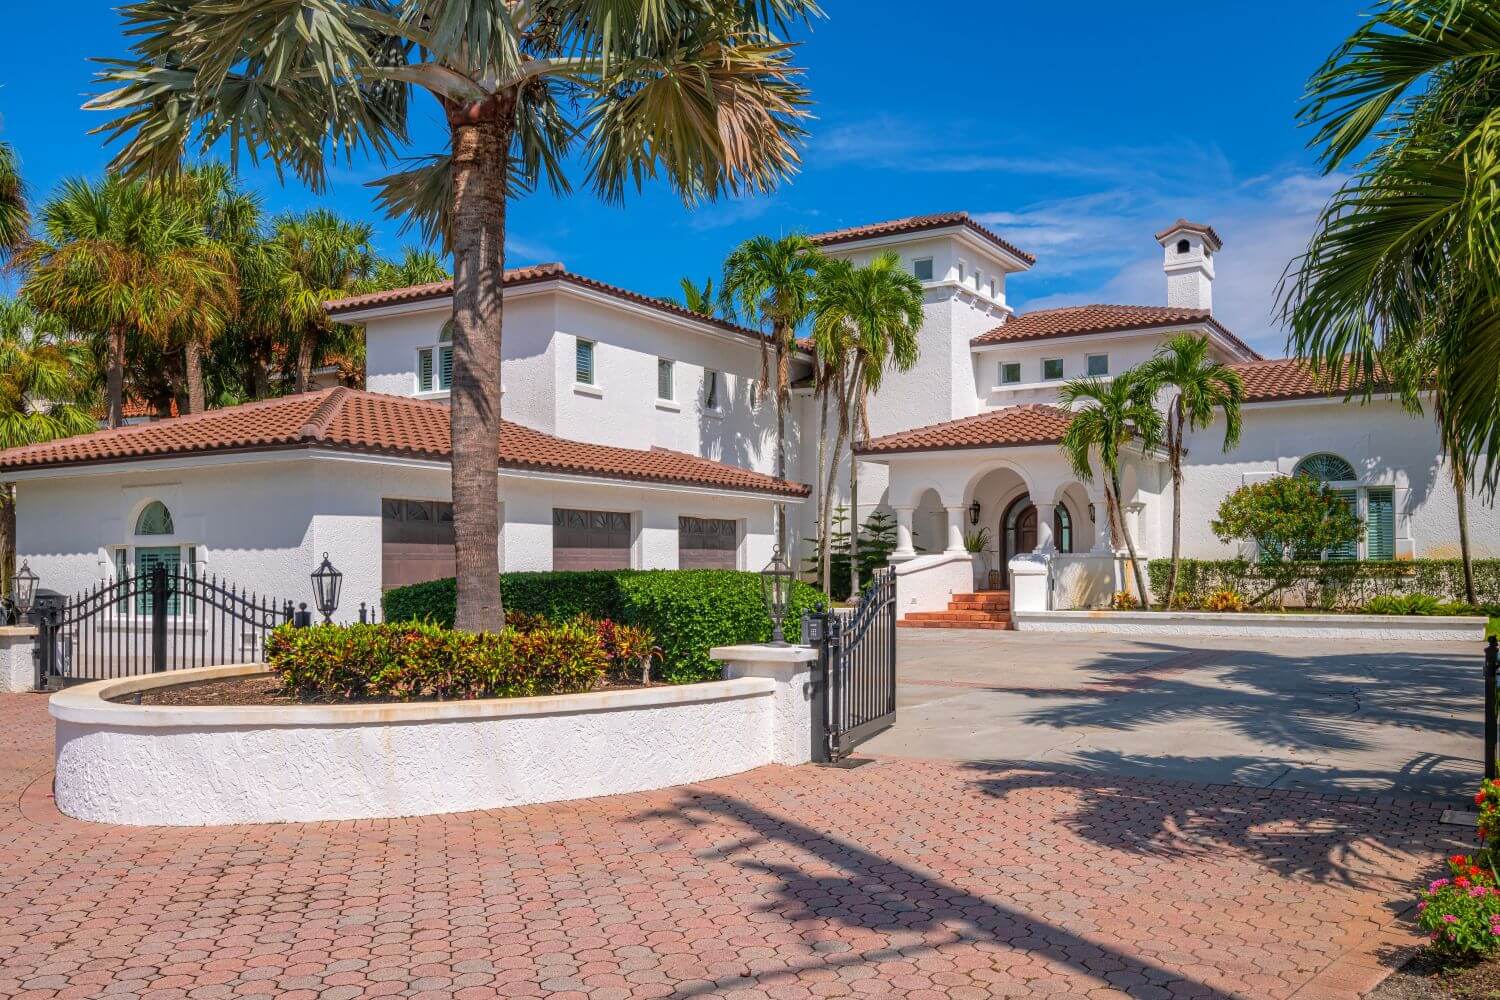
The clients were looking to purchase a high-value second home in Spain and required a mortgage solution that would provide low monthly payments while allowing them to make substantial capital repayments over the longer term.
Introduction:
-
£1.3m borrowing requirement for the purchase of a property valued at approximately £1.9m
-
The clients were looking for an interest-only mortgage to keep monthly commitments low
-
They wanted the ability to make substantial lump-sum repayments over the following five years
-
Flexibility was required around when the capital could be repaid, so we needed to ensure the facility had no early repayment penalties
-
A solution was required that could take a holistic view of the clients wealth and assets, alongside their current income
The Client:
The clients, aged 54 and 55, were looking to purchase a second home in Spain for approximately £1.9 million. They had significant liquidity but not enough to cover the full purchase. With a relatively low current earned income their borrowing requirements were more complex than a conventional residential mortgage application.
Their priority was to secure an interest-only mortgage that would keep monthly payments low while giving them the flexibility to make substantial capital repayments over the following five years without incurring early repayment charges.
The Situation:
The clients had a strong overall financial position, but their current income did not fully reflect their wider wealth or their anticipated ability to repay the mortgage.
Their assets included more than £1.1 million available through directors' loan account balances, approximately £150,000 in cash savings and more than £900,000 in liquid pension assets available for future drawdown. They also held a pension-owned commercial property worth more than £2 million, generating approximately £150,000 a year in rental income.
In addition, their mortgage-free UK residence was valued at approximately £2 million, while the husband had a future employment entitlement of around £200,000 per annum from February 2027.
The challenge was therefore not simply finding a lender willing to provide the required level of borrowing. It was finding a lender prepared to assess the clients' overall wealth, assets, liquidity and future repayment strategy rather than focusing primarily on their current earned income.
Our Solution:
The case was referred to Aria Finance, and, within one working day, our team had identified a private bank able to structure a high-net-worth mortgage solution around the clients’ wider financial position.
Following a detailed fact-find and recommendation process, the application was submitted and received full approval, subject to valuation, within 10 days of the initial referral.
Aria proactively progressed the onboarding and legal work while the valuation was being arranged. This helped maintain momentum and ensured the case continued to move forward while the valuation was outstanding.
The property was subsequently valued at a lower figure than the clients had anticipated, requiring the original borrowing requirement to be restructured.
The mortgage offer was issued within six weeks of the initial referral, and the case completed within two months.
The resulting interest-only, two-year tracker mortgage provides the clients with low monthly payments and the flexibility to make lump-sum capital repayments without early repayment penalties, supporting their longer-term repayment strategy.
Benefits & Results:
The clients were able to complete their Spanish second home purchase with an interest-only mortgage that reflected their wider financial circumstances rather than relying solely on their current earned income.
The structure provides low monthly payments and allows the clients to make lump-sum capital repayments without early repayment penalties. This gives them flexibility to reduce the outstanding mortgage over the coming years using their directors' loan account funds, pension assets and other available resources.
The case also demonstrates the value of specialist mortgage advice where a client’s wealth is held across multiple assets and income sources. Aria’s established relationships with private banks enabled the team to identify a lender able to take a holistic view of the clients’ wealth, assets and future income, rather than assessing the application on current earnings alone. The resulting solution supported both their immediate property purchase and their longer-term repayment strategy.